Questions for Public Administrations

Between the evening of 12 November and the afternoon of 13 November 2026, Microsoft 365 services (Exchange Online, Outlook, Teams, Copilot) were unavailable or degraded in at least 70 countries for almost 24 hours. According to Microsoft, the cause was a network capacity upgrade, not a cyber attack. Public bodies reporting disruption included parliaments, courts, police forces, schools, local authorities, and health services. Source: BBC News live coverage, 13 November 2026.

We ask the following questions of the public administrations concerned. The same questions apply to any organisation that depends on Microsoft 365 for its daily operations.

Impact

  1. Which services of your administration were interrupted or slowed during the outage, and for how long?
  2. Which activities were postponed or cancelled as a result, such as medical appointments, court hearings, administrative procedures, and parliamentary work?

Preparedness

  1. Was the unavailability of a single vendor’s services included as a scenario in your risk assessment before 12 November?
  2. Which contingency plans existed for email, calendars, document access, and user authentication? When were they last tested, and with what result?
  3. Will you publish those plans?
  4. Which communication channels were used while email was unavailable? Who authorised them, and who is responsible for the protection of the personal and confidential data that passed through them?

Critical Functions

  1. Which clinical functions, including referrals, prescriptions, and appointment scheduling, depend on a single vendor’s email and calendar services? Which of them have a fallback that does not depend on that vendor?
  2. Which court and justice procedures depend on the same services, and which have an independent fallback?

Procurement

  1. How much public money was spent on Microsoft licences and cloud services in each of the last five years?
  2. How much public money was spent on open-source software and open-standards solutions over the same period?
  3. Do your tenders require data portability, open document formats, and a tested exit strategy? If not, for what reason?
  4. Do your contracts provide for service-level penalties or compensation in case of interruption? Has any claim been made?
  5. Under your current contracts, who decides when your administration regains access to its own documents and communications?

Follow-Up

  1. Parliamentary and governmental reports had already identified dependence on a small number of foreign providers as a strategic vulnerability. Which procurement decisions changed as a result?
  2. Will you commit to a public audit of your vendor dependencies, to be completed by a stated date, with a named person responsible and a dedicated budget line?

For twenty years we proposed answers to these questions to politicians and public servants. We were met with smiles.

In light of the outage, we ask whether you are now willing to listen. Our proposed answers carry no company or product name. They carry two concepts: open source software and open standard document formats.

1,000 donations, and counting

Yesterday, The Document Foundation received over 1,000 donations in a single day, setting a new record. While we take no pleasure in the operational problems faced by other organisations, the timing suggests that many people are reconsidering their reliance on a single cloud service provider for their documents. With LibreOffice, your documents are stored locally, and ODF files belong to their authors and not to a service provider.

To everyone who has donated, thank you. Your support is what keeps this software and these standards independent.

The past, present and future of office suites

Summary

The office suite market is large, profitable and growing, and this attracts new entrants: low-cost clones, open-core products and, more recently, suites built largely with artificial intelligence. Most of them compete on price and on native support for OOXML, a format whose evolution remains in practice under Microsoft’s control.

When features can be reproduced cheaply, what distinguishes a suite is who governs the document format and the software, and therefore who controls the content. This is the question of digital sovereignty, and its outcome will depend partly on political decisions, and partly on software features.

The 1980s and 1990s

The office suite sector emerged in the 1980s and developed in the 1990s, when Microsoft Office established itself as the leading product, with a market share of over 90% according to Microsoft unofficial statements at their events.

Some may remember the main competitors: Lotus SmartSuite, WordPerfect Office and StarOffice, the ancestor of OpenOffice and LibreOffice. Fewer will recall Anywhere Office, Ability Office, Pro PC Suite 2001 and ThinkFree Office. Ability Office still exists, and ThinkFree Office is now called Hancom Office.

By the end of the century Microsoft Office dominated the sector, while all other products had a barely noticeable market share or had disappeared altogether.

The sector has always been lucrative: the products meet a universal need, while development and sales costs are low relative to volumes, so margins are potentially extremely high. For this reason all the major software vendors tried to enter the market, and the first clones emerged, competing solely on price.

Market presence, however, was just one of the factors contributing to success. Other factors were bundling with the Windows operating system, lock-in through document formats and pricing.

The two decades between 2000 and 2020

Sun Microsystems, which had acquired StarOffice, released its source code in 2000, and OpenOffice.org 1.0 followed in 2002: the first FOSS suite to reach a mass audience. Version 1.0 offered only a glimpse of the suite’s potential, and version 1.1 was usable but still limited. Only version 2.0, released in 2005, made OpenOffice a genuine competitor to the market leader.

For several years the rivalry between the proprietary suite and the FOSS suite played out on two fronts: large migration projects and document formats.

At the time, migrations seemed to signal an irreversible trend, but this proved an illusion. Microsoft deployed all its commercial muscles and started to talk to politicians. Since 2012, the company has been one of the biggest spenders on lobbying in Brussels (based on data from Corporate Europe Observatory and Lobby Facts).

The battle over file formats was most prominent between 2006, when ODF was standardised by ISO/IEC, and 2008, when the proprietary OOXML format was standardised through a process we have already described in a previous blog post and will not revisit here.

In 2010, following Oracle’s acquisition of Sun, the community created The Document Foundation and LibreOffice. In 2011, Oracle was effectively forced to donate the OpenOffice.org source code to the Apache Software Foundation in order to honour a contract – due to expire in 2014 – that IBM had signed with Sun Microsystems, and which allowed it to use the OpenOffice.org source code whilst disregarding the open-source licence.

The format battle then faded into the background, as IBM decided to abandon the ODF advocacy project at OASIS to use the money to fund the development of Apache OpenOffice and fight the growth of LibreOffice. It resurfaced in 2024 with the concept of digital sovereignty and the announcement of several large scale migrations to open source software, such as the German province of Schleswig-Holstein and the Austrian Army.

Between 2010 and 2020 the sector also evolved with the arrival of cloud-based suites, which started a new battle for market share between Microsoft and Google. Given the sector’s renewed growth, a new generation of clones emerged: programs that are almost always limited in functionality, copy the market leader and compete on licence cost.

Some of these clones, in order to disguise their commercial operation, release a basic version under an open-source licence, often modified so as to prevent forking. Such a licence no longer meets the Open Source Definition, and the product is in practice freeware, while the full-featured version is sold separately (the “open core” model).

Naturally, these programs support the OOXML format natively, because they aim at a low-cost replacement, not at migration, that is, a paradigm shift that would give users full control over the software and its content.

By digital sovereignty we mean the ability of a user or institution to control its documents and software: to open documents with any implementation, to fork the code, and to choose where data is hosted and who operates the service.

OOXML is formally an ISO standard, but its reference implementation remain with Microsoft. As long as this is the case, Microsoft retains control over the content: the user saves money, but sacrifices digital sovereignty.

The current situation

The reason for the renewed interest in the office suite market lies in the size of the market itself, which is worth tens of billions of dollars and therefore whets the appetite of software companies. Even a 1% market share is worth a very significant sum, sufficient to justify the investment.

As a reference point, we use public data from the “Office Productivity Software Market Report 2026” by Business Research Company, a US-based market analysis firm. The office productivity software market reached $50.73 billion in 2025 and is expected to grow to $81.83 billion by 2030, at a CAGR (compound annual growth rate) of 10.1%.

We add some figures relating to Microsoft and Google.

Microsoft 365 Commercial generated $102 billion in fiscal year 2026, an increase of 16%. Paid licences for Microsoft 365 Copilot exceeded 30 million by the end of June 2026, which on analyst estimates is about 6 to 7% of the paid commercial user base.

Google Workspace is estimated to have over 3 billion users and over 11 million paying customers. The user figure includes free Gmail accounts, so it is not comparable to Microsoft’s paid subscriptions.
Technographic data from 6sense, another US-based market research firm, attributes 50.34% of the office productivity category to Google Workspace and 45.46% to Microsoft 365 (figures are based on corporate domains). Measured in corporate licences and revenue, Microsoft is clearly in the lead.

According to 6sense, 64% of organisations use both suites. This figure is only indicative, but it points to an increasingly widespread overlap between office suites, which is not limited to Microsoft 365 and Google Workspace. For LibreOffice, based on hands-on experience with large organizations, we estimate that 50% of users also use another office suite, depending on their needs.

We are therefore talking about a market of enormous economic value, and these figures refer almost exclusively to licences, not to the ecosystem. If we include value added consultancy services, which are a necessary component of every implementation in public bodies and companies, the total is likely to be significantly higher.

Analysts do not provide precise data on this, so we rely on a rough estimate based on experience: value-added services are worth about 25% of the value of licences. On the analysts’ forecast, the 2030 market would then be worth about $102 billion ($81.83 billion plus 25%). One percentage point of market share is therefore worth $1 billion a year to a commercial vendor.

This figure does not accrue to free software, but it explains the incentive for new entrants. It also explains the emergence of a new type of office suite: so-called “clones” developed largely with artificial intelligence.
At present we remain extremely cautious about the use of artificial intelligence in software development, but we recognise that views differ, and we are monitoring the evolution of these applications closely.

The strategic consequence does not depend on that debate: if the cost of reproducing a feature set collapses, features stop being the main barrier to entry. What remains is the governance of the format and of the code, the strength of the community, and the long-term maintenance of the software.

A glimpse into the future of office suites

Over the last twenty years we have read contradictory forecasts: the total disappearance of the sector, or only of the desktop suite, and the opposite, a strong growth driven by announcements of new operating systems, software paradigms or hardware platforms.

One thing is certain: the office suite market has gone through periods of slight contraction, probably normal fluctuations, but overall it has grown, and in our opinion it will continue growing for the foreseeable future.

Today, the installed base consists of around 2 billion desktop and laptop computers, based on active devices reported by manufacturers, plus devices that nobody counts because they are second- or third-hand, found mainly in poorer countries that are overlooked by technology usage statistics.

The integration of AI assistants into the suites adds a further dimension. With more than 30 million paid Copilot seats, Microsoft has shown that there is a market for it.

Overall, this is an extremely interesting potential market, where there is room for all types of office suites, desktop and cloud-based, and for all development strategies. On the other hand, success is not just related to number of users as there are market dynamics which depend on political decisions that go beyond the value of the software itself.

However, the location where documents are processed – whether locally or in a provider’s cloud – and the ability of artificial intelligence tools to read and write in open formats remain issues linked to the question of sovereignty. We have already expressed our views on these matters in several blog posts: nothing should interfere with the user’s right to decide on their own content.

LibreOffice will continue to be a key player. Downloads and donations grew substantially in 2026 (as of 31 October, downloads +26% and donations +44 in term of numbers), which reflects a steady improvement in the quality of the software and in the reputation of the project.

The practical conclusion is that LibreOffice and ODF compete on a different axis from the clones: not feature parity at a lower price, but open governance of the format and of the code.
LibreOffice Migration Workshop in Nairobi, Kenya

LibreOffice Migration Workshop in Nairobi, Kenya

When governments, organisations and companies move to LibreOffice – as we’re seeing in Austria, Germany and other countries – they usually enlist the help of Certified Migration Professionals.

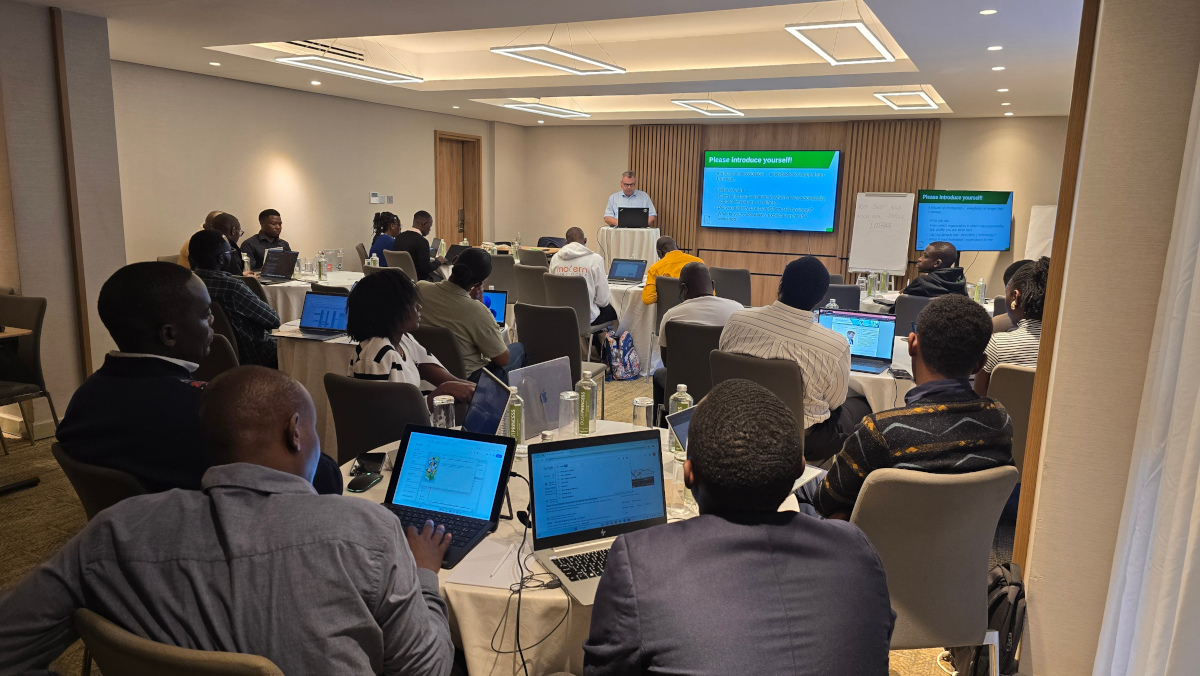
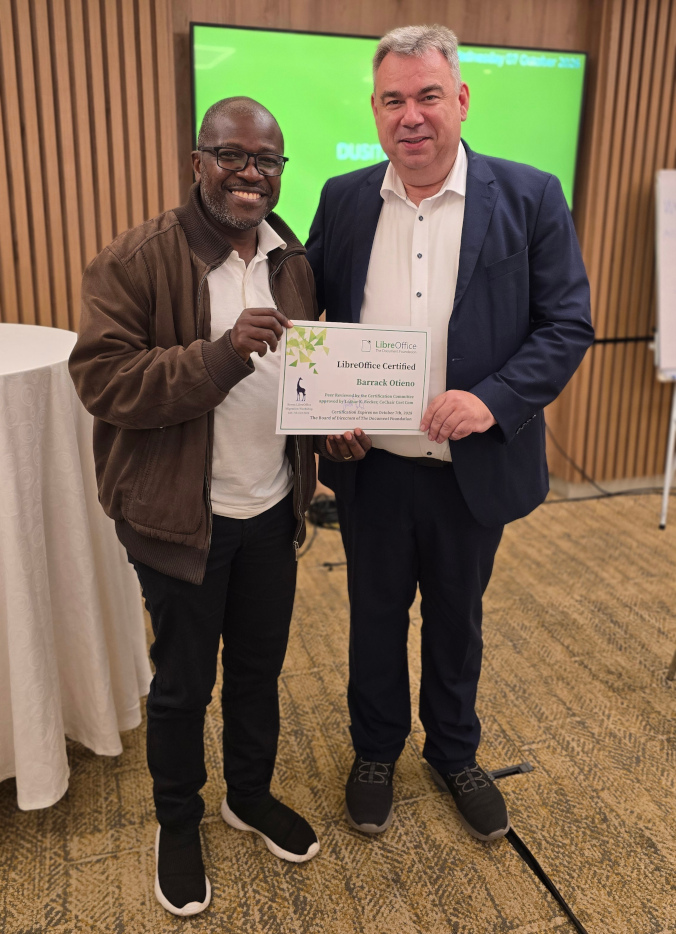
Recently in Nairobi, the capital city of Kenya, we held a LibreOffice Migration Workshop. 40 attendees registered, from the public and private sectors, and the session was conducted pro bono by Lothar Becker, co-chair of LibreOffice’s Certification Committee. The goal of the workshop was to grow and foster the LibreOffice Technology ecosystem by supporting partners and government organisations in facilitating migrations to the suite.

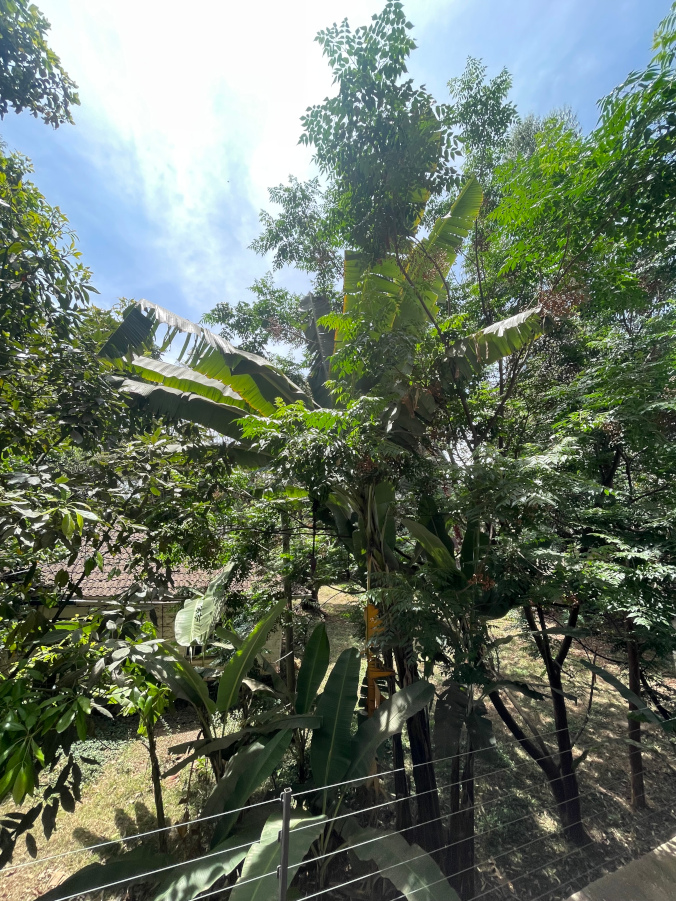
It took place in the conference rooms of a hotel in central Nairobi, with a great view:

LibreOffice Migration Workshop in Nairobi, Kenya

The event was hosted and funded by the Kenya branch of GIZ Germany, along with The Document Foundation, the non-profit entity behind LibreOffice. The first two days focused on LibreOffice, covering best practices for migrations to LibreOffice Technology, with the first day being more user-centric and looking at the user interface and features of the software. There was also a general introduction to TDF and open source.

Then, the second day focused more on the migration process, providing deeper insights into migration and training protocols. Other topics included digital sovereignty with the Open Document Format (ODF) and other certification processes with TDF.

LibreOffice Migration Workshop in Nairobi, Kenya

On the third day Lothar gave a talk called “Open source Community of Practice” in his capacity as OSBA board member. The talk focused on “Open Source as an Enabler of Digital Sovereignty & Innovation” with respect to DPI, Free and Open Source Software, open standards, and AI.

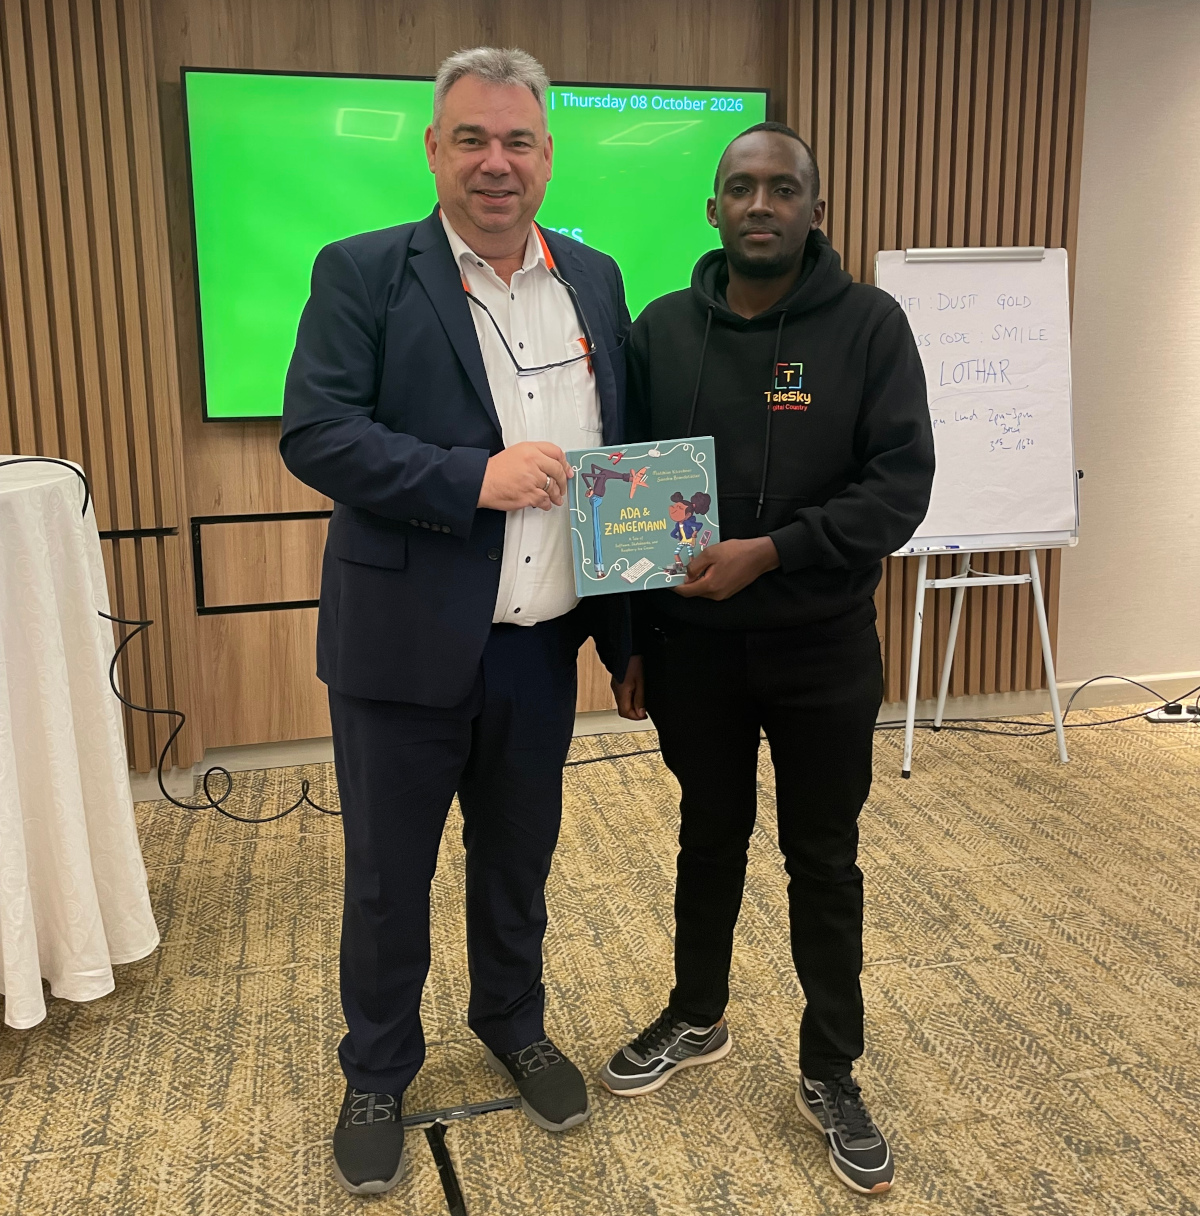
Special thanks to Carsten Glöckner, Amrit Labhuram, their team from GIZ Kenya for all their help and support in organising these events. Lastly, during the workshop Lothar had the opportunity to learn about the valuable work of the Telesky Foundation for digital participation of all children in Kenya from John Mbugua. Lothar handed over a book about “Ada & Zangemann” from Matthias Kirschner (Free Software Foundation Europe).

LibreOffice Migration Workshop in Nairobi, Kenya

The Document Foundation has its own visual identity

Since its founding in 2010, The Document Foundation has used the LibreOffice logo to represent itself. This was a deliberate choice: a young project needed to concentrate recognition on a single name and a single mark, and LibreOffice was the name people needed to know.

Sixteen years later, the foundation’s work extends well beyond the product. TDF takes part in the development of the Open Document Format (ODF) standard, contributes to policy discussions on interoperability and digital sovereignty, and works with public administrations, standards bodies and other open source organisations. In these contexts, the foundation speaks as an institution, not as a software project, and it needs a signature of its own.

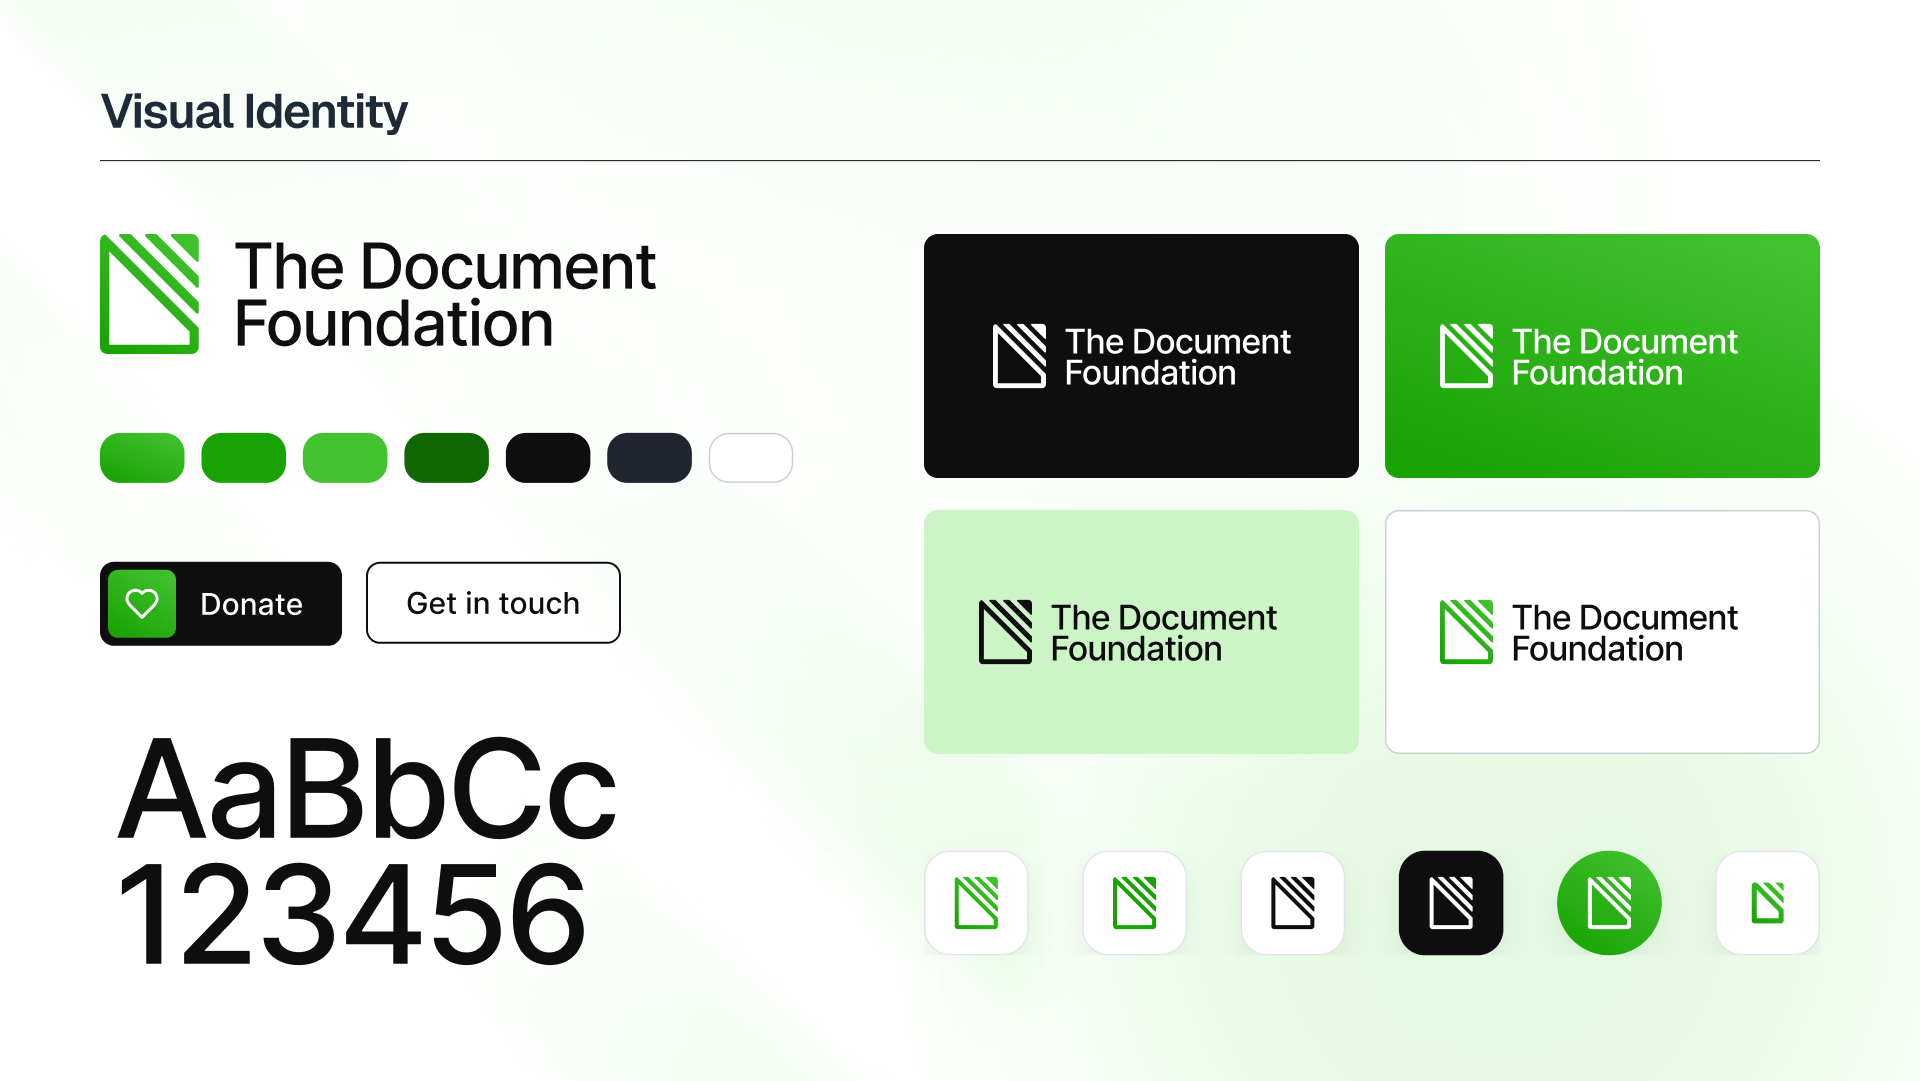
For this reason, we have worked with Ura Design to create a visual identity for The Document Foundation, consisting of a logo, a colour palette and a typeface. The logomark is a stylised page, a reference to the documents and the document standard at the centre of the foundation’s mission. It is shown here in its primary version.

The colour palette is built around the green of the logo, with a neutral scale for text and backgrounds. All the text and background combinations recommended in the guide meet the WCAG 2.1 contrast requirements, so that materials produced with the new identity remain accessible.

The typeface is Inter, designed by Rasmus Andersson and released under the SIL Open Font License. It is used for the wordmark of the logo as well as for all texts, from reports and presentations to the website. A typeface released under a free licence is consistent with the foundation’s mission: anyone can use it, in LibreOffice or in any other application, without restrictions.

Nothing changes for LibreOffice. Its name, logo and visual identity remain exactly as they are. The two identities have different roles: LibreOffice identifies the software, while The Document Foundation identifies the organisation that hosts LibreOffice and its community, and represents them in the wider world.

The logo package is available for download at https://tdf.io/tdflogo. It includes vector (SVG) and raster (PNG) versions of the logo, a favicon, and avatars for social media. The Visual Identity Style Guide explains which version of the logo to use in each context, and sets out the colour palette, the typography and the rules for applying them consistently. Use of the logo is governed by TDF’s trademark policy.

Over the coming months, the new identity will replace the LibreOffice logo on the foundation’s website, social media accounts and institutional documents. Templates for LibreOffice Writer and Impress will also follow. If you maintain pages or materials that refer to The Document Foundation as an organisation, please update them with the new files. Pages that refer to LibreOffice should continue to use the LibreOffice logo.

Questions about the visual identity and its use can be sent to italo@documentfoundation.org

State of the Project (October 2025 – September 2026)

We are releasing the State of the Project Slide Deck, which is updated quarterly and based on data extracted from the LibreOffice dashboard and the Matomo repository between 1 October 2025 and 30 September 2026.

Over the course of 12 months, 297 developers worked on the source code, making a total of 11,676 new commits (Git). Of these, 2,596 (22%) were provided by 228 volunteer developers (77%), 4,818 (41%) by 11 developers from The Document Foundation (4%), and 4,636 (37%) by 58 developers from seven ecosystem companies (19%).

The slide deck is also a tribute to the top 20 Git and Gerrit committers, the top 20 Bugzilla issue submitters, the top 20 Discourse contributors, and the top 20 Weblate translators. Thank you to all of them and to all the other contributors.

Examining donations and downloads, the trend during the first nine months of 2026 confirms the positive trend that began in early 2025. The number of donations and downloads increased significantly in August and September 2026 thanks to a number of small but important changes to the marketing strategy and donation mechanism. It is important to note that the figures refer to the number of transactions, rather than their value, which is available via the ledgers published on The Document Foundation website.

You are invited to view the slides and download the file to compare it with the previous slide decks published in January, April and July. The next slide deck will be available in January and will cover the 12 months between 1 January 2026 and 31 December 2026.

In January 2026, we started publishing these slide decks to provide a transparent overview of the project’s progress through some of the most significant development, download and donation data collected by the TDF marketing team.

Download the slide deck in English